
Greater Phoenix Blue Chip
NO QUICK OR OBVIOUS WAY OUT
Third Quarter, 2026
Elliott D. Pollack & Company
Over the last few quarters the outlook for the Greater Phoenix single-family market has grown steadily dicier. Many factors are at work: higher interest rates, high prices, non-housing inflation that makes it harder to save for a down payment or afford a mortgage payment, a larger share of income spent on housing, and rising costs and longer lead times from unnecessary regulation (overzealous local governments have increased the cost and time it takes to develop land and build homes). These are only a few of the many issues that have delayed the milestones that historically marked the beginning of economic adulthood and allowed young adults to start climbing the economic ladder that is the American Dream. The result is a very different world for the current generation of first-time homebuyers. This is true despite what have been stellar age demographics for housing.
The big question has been when will these factors normalize and release the huge underlying demand for homeownership. But is this time different? Will the current parade of horribles that surround the single-family market permanently shift people towards renting rather than owning a home?
The conventional view of how a housing recovery would put single-family ownership, marriage, and family formation back on track was that, over time, mortgage rates would decline, new homes would be smaller and have fewer amenities, there would be some decline in construction costs, and home prices relative to incomes would ease. The transfer of wealth from Boomers to later generations would also help. All of this would release the huge pent-up demand created by the economic events of the last four years.
But now events are causing some to question this scenario. Consider the issues. Will interest rates stay higher for longer because inflation is staying higher for longer? The answer is obviously yes. The competition for funds from a government that seems hooked on deficit spending is enormous. Government borrowing is expected to stay higher for the next decade. Combined with the huge demand for funds to build AI and the electrical generation needed to power it, this will continue to put pressure on money markets. Economists continue to debate the cause of today’s high inflation. One view holds that it reflects a string of temporary shocks – namely the implementation of new tariffs and the Iranian situation’s effect on oil prices – and that conditions will return to normal once those events resolve. The other holds that inflation has become embedded in expectations and will take a recession to cure.
Downward pressure on housing prices relative to incomes, combined with a more coherent tariff policy and a calming of the Iranian situation, will probably help. How far rates will fall, though, remains to be seen. That said, even though the current annual inflation rate is roughly half of its post-pandemic peak, further declines in inflation and rates are unlikely to come quickly.
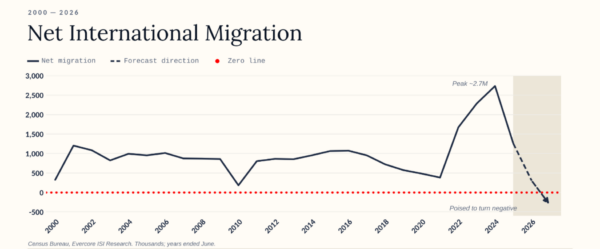
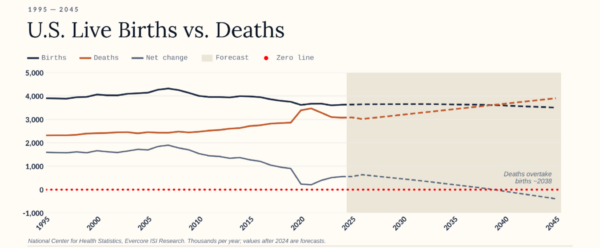 Another issue is underlying demographics. For example, natural population growth drivers in the U.S. continue to deteriorate. Births over deaths are now a fraction of what they have been historically. For both economic and sociological reasons, the current child-bearing generation in much of the world is having, or soon will have, too few children to replace those who die. As a result, the population will soon peak and then decline. In the U.S., many of these effects have been masked by continued migration from other countries, including a surge of immigration 2021 through 2024. Economic and housing research generally views immigration as a net driver of increased housing demand and higher prices/rents, rather than a positive force for affordability. But it can also help to revitalize underinvested neighborhoods and expand the workforce needed to build more homes. Immigration first slowed dramatically in 2025 and it is now going negative. Thus, while these low immigration policies may help in some ways, another driver of housing demand is under pressure.
 Overall, it looks like the recovery in single-family housing will be a difficult one.
As for Greater Phoenix, single-family permits are expected to remain flat or down in 2027. On the other hand, multifamily permits are expected to increase significantly in 2027 before slowing in 2028 while apartment absorption is expected to stay higher than normal.
At least Greater Phoenix continues to be a winner in the net population movement between states. That is a positive that should remain.
GREATER PHOENIX BLUE CHIP: RESIDENTIAL
| 2026 | 2027 | 2028 | ||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Single Family Permits | Multi-Family Permits | Apt. Vacancy (Q4 %) | Apt. Absorp. | Single Family Permits | Multi-Family Permits | Apt. Vacancy (Q4 %) | Apt. Absorp. | Single Family Permits | Multi-Family Permits | Apt. Vacancy (Q4 %) | Apt. Absorp. | |||
| Elliott D. Pollack & Co. | 19,350 | 9,400 | 9.5% | 12,000 | 21,250 | 9,100 | 9.0% | 13,000 | 22,100 | 11,500 | 8.5% | 14,000 | ||
| Griffin Consulting | 21,300 | 7,000 | 8.4% | 12,750 | 20,500 | 9,250 | 8.0% | 12,250 | 19,750 | 9,500 | 7.8% | 11,750 | ||
| Land Advisors | 20,000 | 10,375 | 6.9% | 19,167 | 20,375 | 9,375 | 6.0% | 17,000 | 13,625 | 11,000 | 5.7% | 16,333 | ||
| Nathan & Associates | 19,500 | 8,000 | N/A | N/A | 21,000 | 7,000 | N/A | N/A | 23,000 | N/A | N/A | N/A | ||
| Southwest Growth Partners | 21,150 | 9,750 | 9.5% | 10,000 | 22,200 | 10,250 | 8.9% | 12,000 | 23,300 | 10,750 | 8.0% | 13,500 | ||
| Univ. of Arizona Eller College | 25,092 | 12,608 | N/A | N/A | 25,849 | 11,161 | N/A | N/A | 26,168 | 10,200 | N/A | N/A | ||
| CONSENSUS | 21,065 | 9,522 | 8.6% | 13,479 | 21,862 | 9,356 | 8.0% | 13,563 | 21,324 | 10,590 | 7.5% | 13,896 | ||